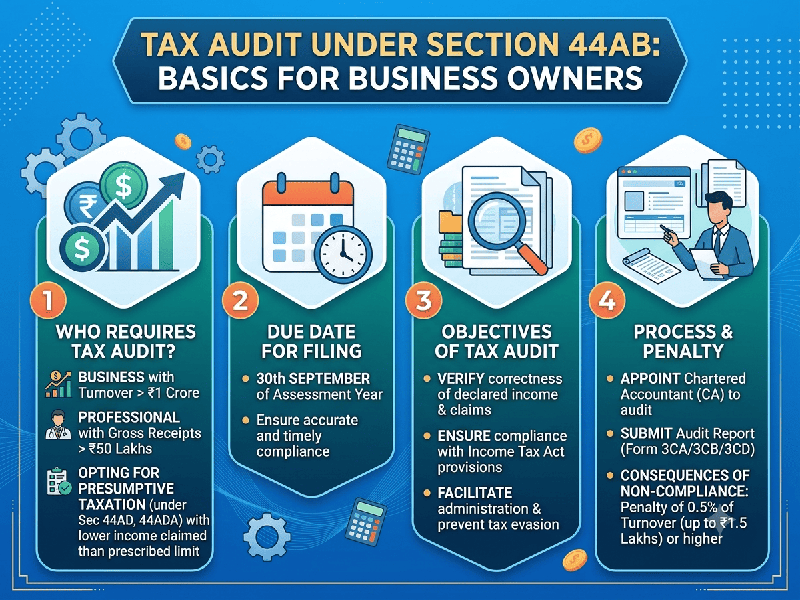
Tax Audit Under Section 44AB: Basics for Business Owners
A Tax Audit under Section 44AB of the Income Tax Act, 1961 is a statutory requirement where a practicing Chartered Accountant (CA) examines a business or professional’s books of account.
1. Audit Report Forms Explained
The tax audit report consists of two key components: the main audit report (Form 3CA or Form 3CB) and the detailed statement of particulars (Form 3CD).
Form 3CA + Form 3CD: Used for entities that are already required to get their accounts audited under another law (e.g., Companies under the Companies Act, 2013).
Form 3CB + Form 3CD: Used for entities that are NOT required to be audited under any other law (e.g., Proprietorships or Partnership firms falling strictly under Section 44AB).
Form 3CD: A comprehensive 44-clause statement covering details on turnover, depreciation, disallowances under tax laws, TDS compliance, and GST reconciliations.
2. Penalty for Non-Compliance (Section 271B)
If a business owner fails to get their accounts audited or fails to submit the tax audit report by the prescribed due date, the tax authority may impose a penalty under Section 271B equal to:
"Penalty"=min(0.5%×"Total Sales / Turnover / Gross Receipts" , "₹1,50,000" )
3. Action Plan for Business Owners
Verify Cash Transaction Percentage: Ensure digital payments/receipts stay above 95% to take advantage of the higher ₹10 Crore threshold.
Reconcile Data Early: Match your General Ledger against GST returns (GSTR-1/3B vs 2B) and TDS certificates (Form 26AS/AIS) prior to audit kickoff.
Appoint a CA Well in Advance: Do not wait until September to assign a Chartered Accountant; allow sufficient time for ledger verification and clause-by-clause Form 3CD preparation.